Notice
No financial advice provided.
Results may vary.
About Malquinos: Clarity in credit risk
Clients ask us one thing: How do you measure credit risk where public data is scarce? Our answer is always the same: evidence, not hope.
Seventy percent of institutional portfolios now include illiquid private credit.
We design robust frameworks that help you quantify and manage risk in this
growing market. Our focus is analytical accuracy, strict model validation, and
continuous peer review. We blend practical finance with advanced statistical
methods, always prioritizing transparent assumptions. Our team translates
complex risk signals into actionable insight, keeping you informed and ahead.
Our vision: empower financial professionals to navigate uncertainty in private
credit with evidence, not guesswork.
Data-first methodology
Our process starts with rigorous data sourcing and integrity checks, ensuring every analysis stands up to external scrutiny and evolving standards.
Innovative risk quantification
We build custom frameworks for quantifying illiquidity, helping clients understand the real drivers behind credit exposures and market dynamics.
Peer-reviewed thinking
Continuous review from independent experts ensures every model reflects current research and regulatory changes, not just yesterday’s wisdom.
Connect with our team
Ready to discuss advanced risk analytics, data-driven models, or your next project? We respond within one business day with clarity and precision.
Say helloCore values guide us
Our commitment: transparency, evidence, and technical discipline drive every project we accept in the private credit Malquinos.
Transparency always
Transparent methods—no hidden steps. Every decision, assumption, and data source is
documented and open to review by independent experts, reducing uncertainty and bias.
Evidence driven
Evidence over opinion—models must be backed by data, not convention. We challenge
assumptions, update methods, and stay responsive to new research in private credit
markets.
Integrity enforced
Integrity is enforced through rigorous checks. Data validation and continuous peer review mean no single voice dominates, and client trust is never compromised.
Technical discipline
Technical discipline means using the right tool for the right task. We avoid
complexity for its own sake, focusing instead on reliable, actionable outputs.
Continuous improvement
Continuous improvement ensures models evolve. We routinely incorporate new
regulatory requirements and sector innovations, staying current and relevant.
Client focused
Client focus means adapting frameworks to unique needs. No two credit portfolios are
identical, and our process reflects that reality.
Peer review culture
Peer review culture—every deliverable is subject to scrutiny from both internal and
external specialists before release.
Practical insight
Practical insight is prioritized over theory. Our work bridges the gap between abstract models and real-world decision-making.
Timeline
Our journey: milestones in risk modeling
Innovation, validation, and continuous improvement: each milestone marks a commitment to analytical rigor and evidence-based practice.
6 events
2019
Start Year
2019
Inception and early frameworks
We launch with a singular goal: address the measurement gap in illiquid private credit markets. Initial frameworks focus on adapting traditional risk tools for portfolios lacking standard pricing data. The foundation is set with strict adherence to transparency and evidence.
Milestone
01 / 06
2020
Peer validation achieved
First independent peer review cycle is completed. Our methodology is shaped by external feedback from finance academics and practicing risk officers. Early adopters cite the transparency of our process as a key differentiator.
Milestone
02 / 06
2021
Data integrity protocol launched
We introduce a proprietary data integrity protocol, formalizing how datasets are sourced and checked before model input. This protocol sets a new internal benchmark, improving outcome reliability across client projects.
Milestone
03 / 06
2022
Recognition and team expansion
Our frameworks are referenced in published sector reviews. The team grows, adding experts in structured credit and automation. Clients report improved clarity in risk reporting for illiquid holdings.
Milestone
04 / 06
2024
Advanced analytics and compliance integration
We expand to cover advanced scenario analysis. Regulatory changes are incorporated into all model reviews. Our work is cited by clients during internal and external audits, reflecting increased trust and adoption.
Milestone
05 / 06
2026
Frameworks evolve for tomorrow
Continuous improvement remains central. We refine our frameworks, applying recent research and responding to evolving market risks. Our focus: anticipate the next set of challenges in private credit risk measurement.
Milestone
06 / 06
Meet our specialists in private credit risk modeling
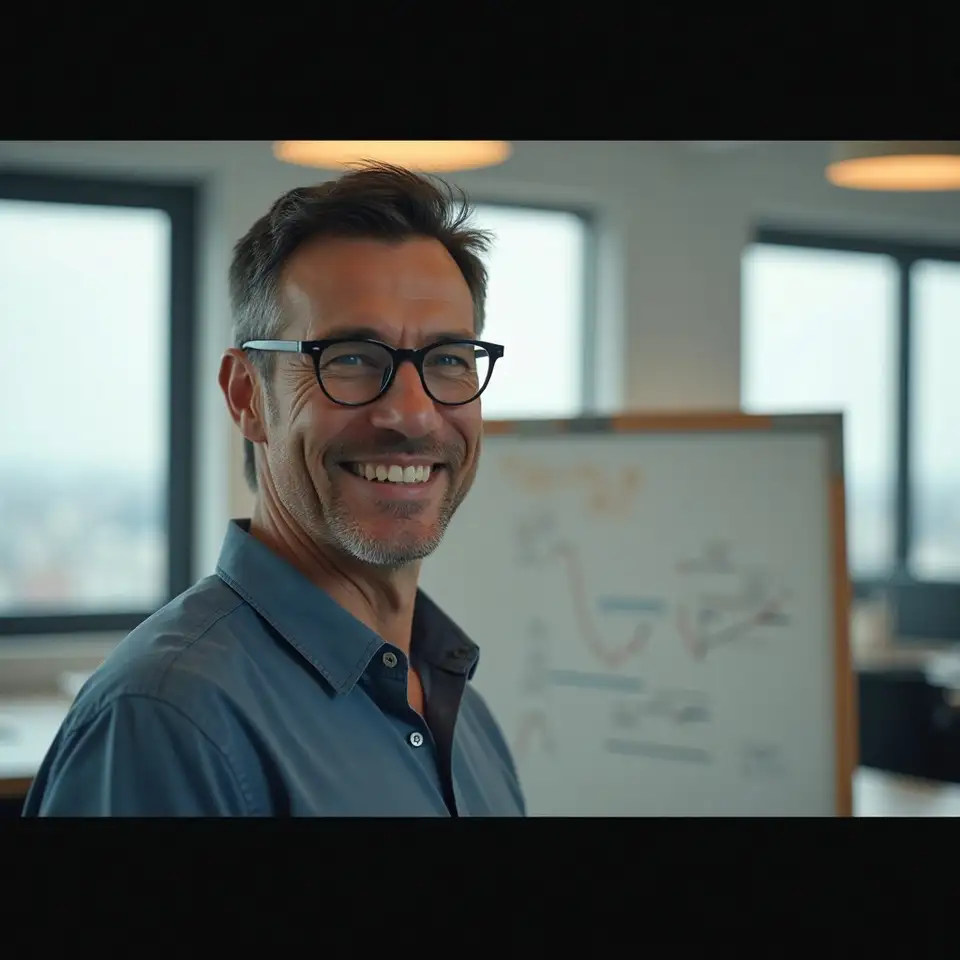
Dr. Marcus Lee, Principal Quant Analyst
Statistical modeling, illiquid asset analysis
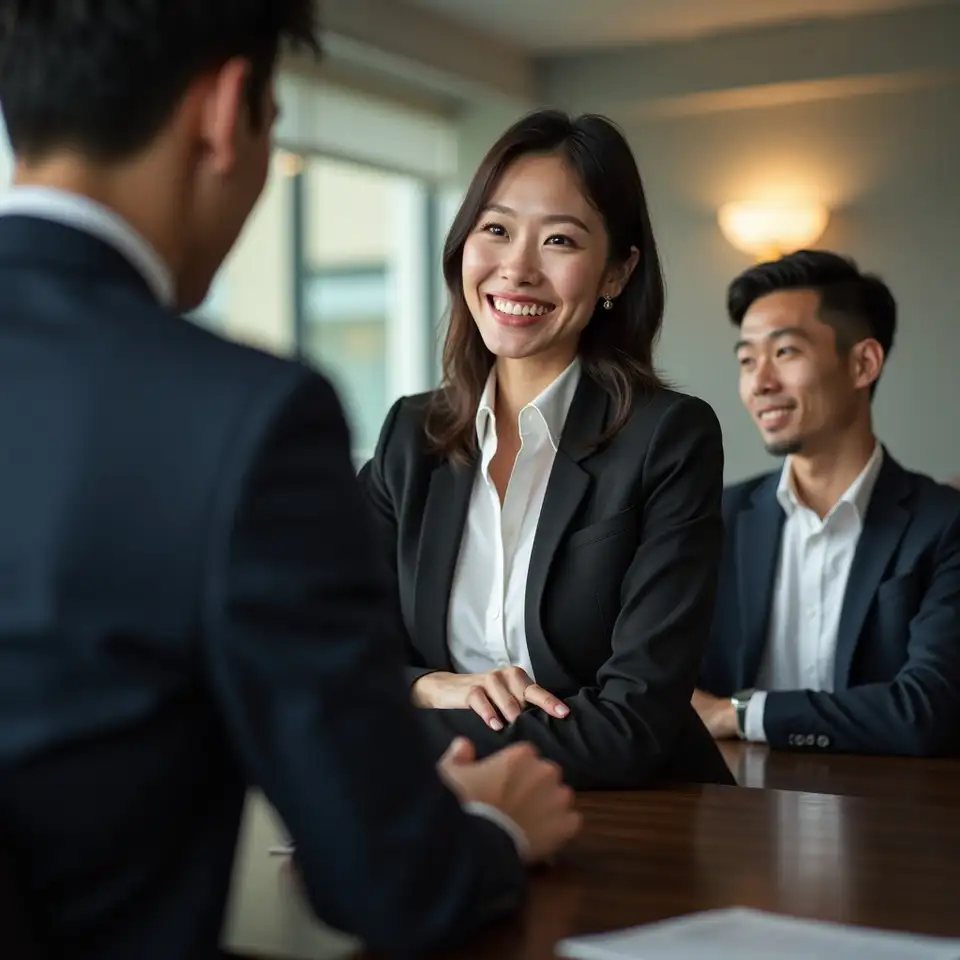
Helen Zhang, Senior Credit Risk Lead
Structured finance, portfolio risk reviews
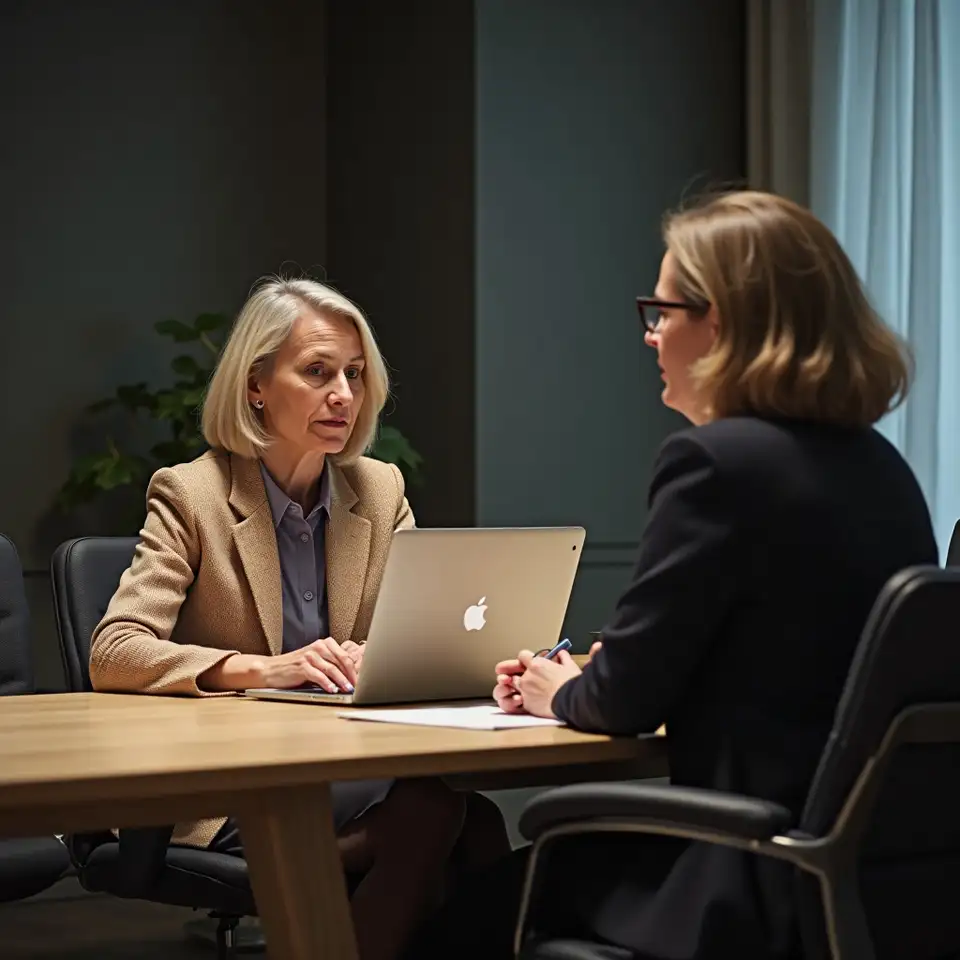
Linda Groves, Head of Model Validation
Model governance, regulatory compliance oversight
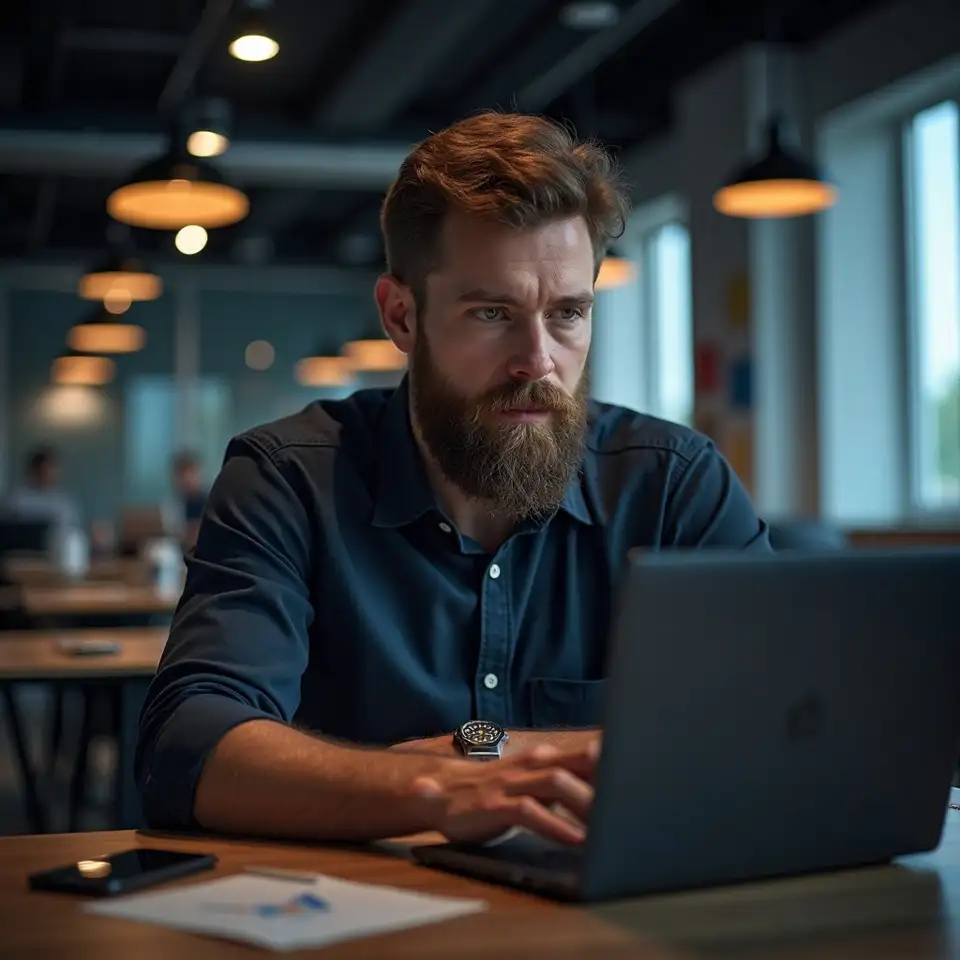
Aaron Patel, Data Integrity Specialist
Data quality, process automation